You paid off your loan in full. You expected your CIBIL score to jump. But when you checked, the score was the same — or it even went down a little. Do not worry, this is very common. Your payoff is not wasted. Here are the 5 real reasons your score did not rise yet, and what you should do next.
Reason 1: The Reporting Lag (Most Common)
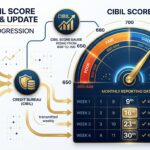
Your lender does not report your closure to CIBIL on the same day. Lenders report in cycles. Under the RBI’s new weekly reporting system (from 1 July 2026), your loan data is updated on the 9th, 16th, 23rd and the last day of the month. So if you closed your loan on the 10th, the bureau may show it only in the next cycle.
What to do: Wait 30 to 45 days and check again. Also ask your lender for a No Dues Certificate (NDC) and a closure letter. These two documents are your proof if the report does not update. Read our full explainer on the weekly CIBIL reporting rules.
Reason 2: Your Credit Mix Became Smaller
Your CIBIL score likes a healthy mix of secured loans (like a home loan) and unsecured loans (like a credit card). When you close your only loan, your mix becomes thinner — and the score can dip a little for some time. This is normal and temporary.
Reason 3: Your Credit Utilisation Went Up
Suppose you closed a loan but your credit card balance is high. If you use more than 30% of your card limit, your score stays under pressure. The payoff helped one side, but the card usage is pulling the other side down.
What to do: Keep card usage below 30% of the limit, and pay the full bill — not just the minimum due.
Reason 4: Old Enquiries Are Still Showing
Every time you apply for a loan or card, the lender does a “hard enquiry”. Too many enquiries in a short time lower your score. These enquiries stay on your report for up to 2 years, and they affect the score most in the first 12 months. A loan payoff does not remove them.
Reason 5: Your Oldest Account Is Gone
The length of your credit history also matters. If the loan you closed was your oldest account, your average history becomes shorter, and the score can fall slightly. Again — this recovers with time and good behaviour on your other accounts.
What To Do Now: A Simple Checklist
- Collect your No Dues Certificate and closure letter from the lender.
- Wait 30–45 days, then pull your fresh credit report.
- Check that the loan shows “Closed” with zero balance. If not, raise a dispute — it must be resolved within 30 days, and delays are compensated at ₹100 per day.
- Keep card utilisation under 30% and pay every EMI and bill on time.
- Do not apply for new loans for a few months. Let the score rebuild quietly.
For a full action plan, read how to increase your CIBIL score.
Conclusion
A score that does not rise after a payoff is almost never bad news — it is usually a timing or mix issue. Give it 30–45 days, verify the closure is reported correctly, and keep your card usage low. Your good habit of closing the loan will show in your score soon.
Frequently Asked Questions
How long after loan closure does the CIBIL score update?
Usually within 30 to 45 days. With weekly reporting cycles (9th, 16th, 23rd and month-end), the closure first reaches the bureau, and the score then moves based on your full credit profile.
Can my score fall after I close a loan?
Yes, a small fall is possible. Closing your only loan reduces your credit mix, and closing your oldest account shortens your credit history. This dip is temporary.
What if my closed loan still shows a balance after 45 days?
Share your No Dues Certificate with the lender and ask them to correct the report. If they do not fix it, raise a dispute with the credit bureau — it must be resolved within 30 days.
Should I close my credit card to raise my score?
Usually no. Closing a card removes its limit from your total credit, which can raise your utilisation percentage and hurt the score. Keep the card, use it lightly, and pay in full.

Sarthak Gupta writes about personal finance, loans and credit for Indian borrowers. His guides on Techy Loan explain CIBIL scores, RBI rules and loan apps in simple language so readers can borrow safely and confidently.