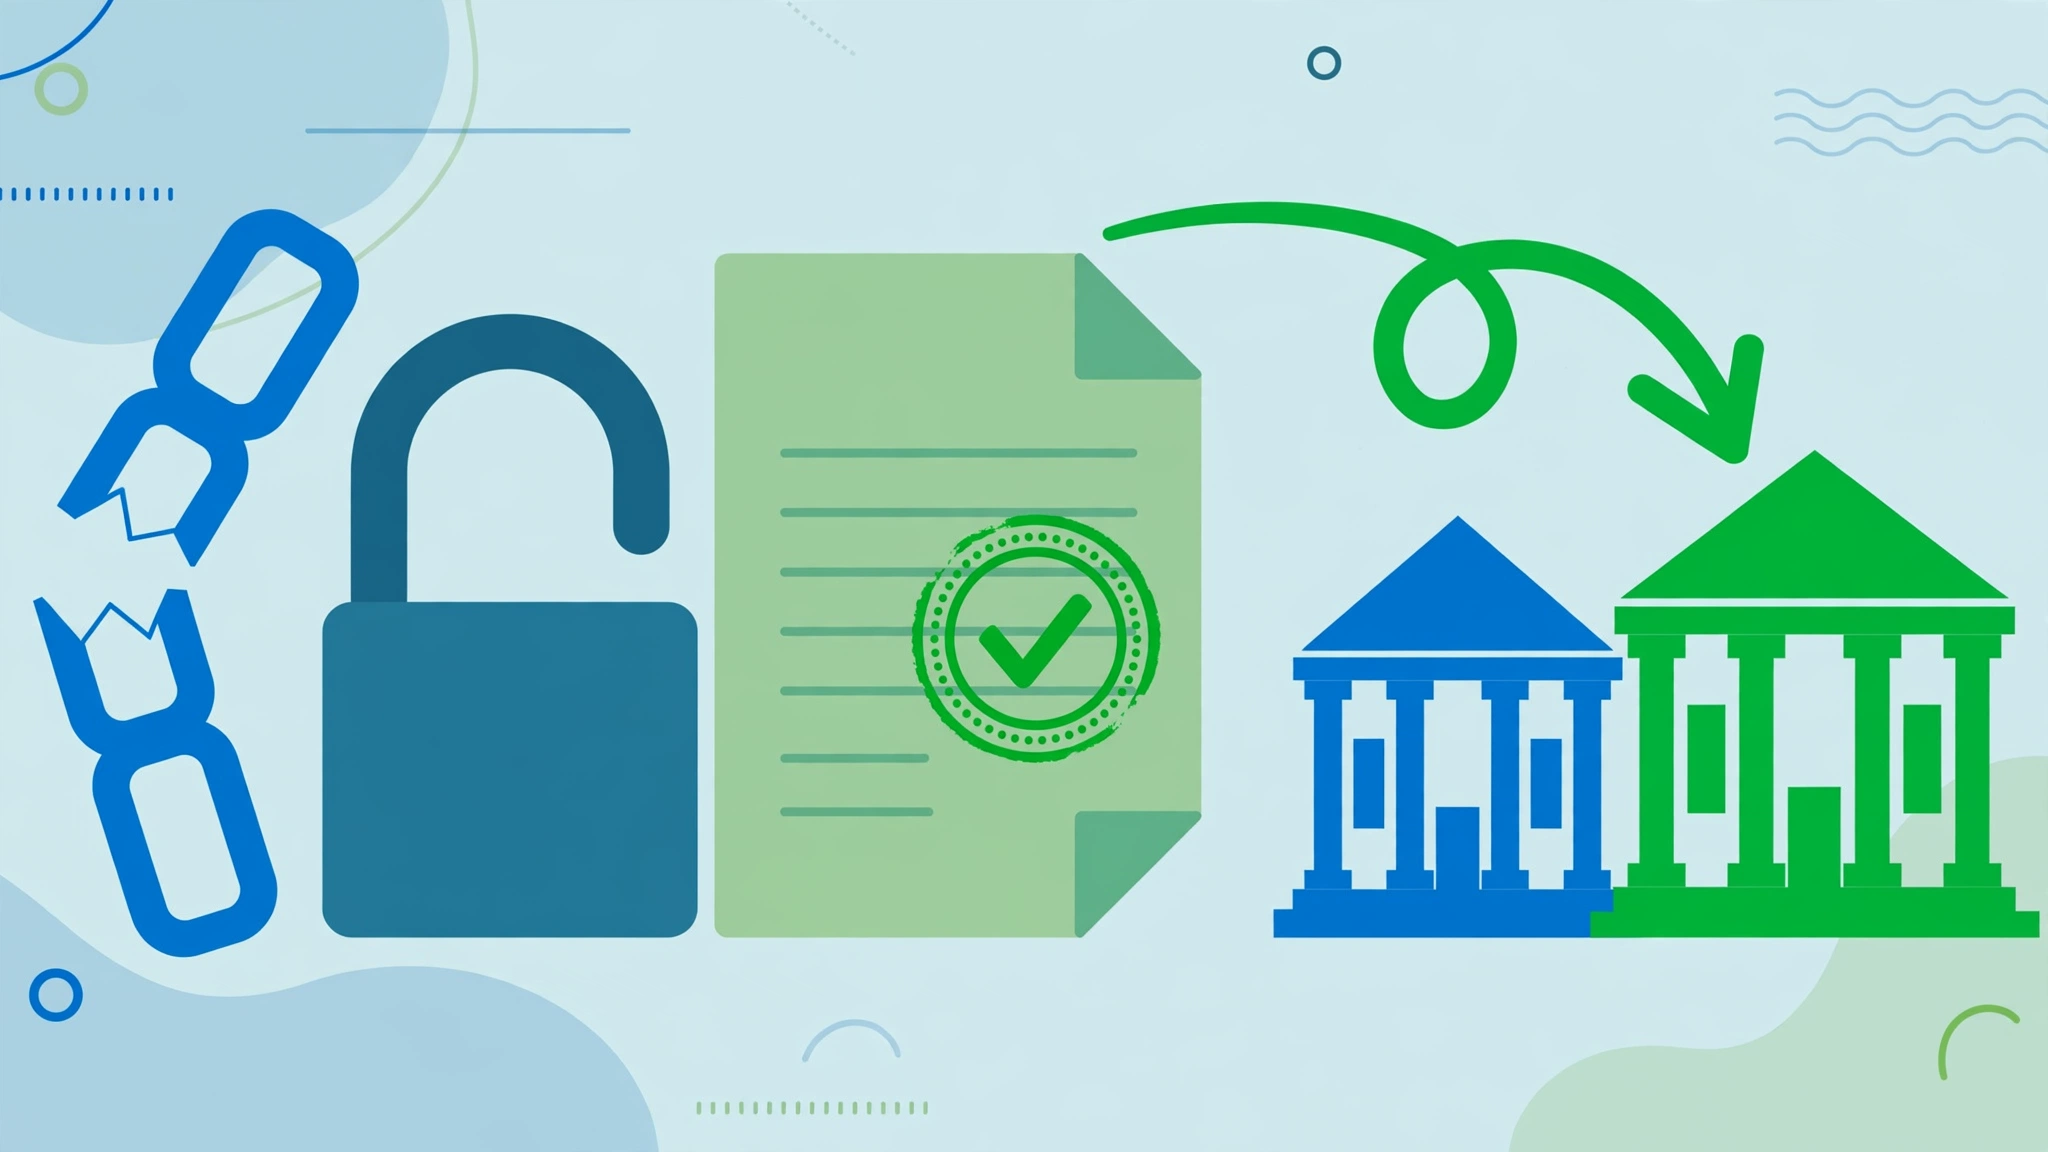
Here is good news most borrowers do not know. Under the RBI’s Pre-payment Charges Directions, lenders cannot charge you a prepayment or foreclosure fee on floating-rate personal loans sanctioned or renewed from 1 January 2026. In simple words: you can close your loan early, or shift it to a cheaper lender, without paying a penalty. Here is how the rule works and how to use it.
What Exactly Did the RBI Ban?
Earlier, if you wanted to close a personal loan early, many banks and NBFCs charged 2% to 5% of the pending amount as a foreclosure fee. On a ₹6 lakh balance, that meant paying ₹12,000 to ₹30,000 just to exit the loan.
Under the new directions, this charge is banned for:
- Floating-rate personal loans taken by individuals for non-business purposes
- Loans given by banks, NBFCs (including upper-layer NBFCs) and All India Financial Institutions
- Full prepayment and part prepayment — both are covered
- Loans repaid from your own money or from a new loan with another lender (balance transfer)
There is also no lock-in period. You do not have to wait 6 or 12 months before you can prepay.
Who Is Not Covered?
- Fixed-rate loans: The ban is for floating-rate loans. On fixed-rate loans, the lender may still charge a fee — it must be clearly written in your sanction letter and Key Facts Statement.
- Business loans (large): The ban covers personal loans and small business loans to individuals and micro/small enterprises. Large commercial loans follow their own agreements.
- Old loans: The rule applies to loans sanctioned or renewed on or after 1 January 2026.
How to Switch Your Loan to a Cheaper Lender (Step by Step)
- Check your current rate. After the October 2026 repo rate hike, your floating rate may have gone up. See our guide on the repo rate hike and your EMI.
- Get offers from 2–3 lenders. Ask for the full cost: interest rate, processing fee and insurance — not just the headline rate.
- Compare total savings. A switch makes sense only if the interest you save is more than the new loan’s processing fee and charges.
- Apply and get the sanction letter. Read the Key Facts Statement carefully before signing.
- Ask your old lender for a foreclosure statement. They cannot add a prepayment charge if your loan is covered. Get a No Dues Certificate after closure — it protects your CIBIL record.
A Quick Example
Suppose you have a ₹8 lakh personal loan at 14% with 4 years left. A new lender offers 11.5%. Over 4 years, the lower rate saves you roughly ₹45,000 in interest. Earlier, a 3% foreclosure fee (₹24,000) would have eaten half your saving. Now, if your loan is covered, the fee is zero — the switch gives you the full benefit.
Conclusion
The prepayment charge ban puts power in your hands. If your personal loan is floating-rate and was sanctioned or renewed in 2026, you can prepay or shift lenders without a penalty. Compare the total cost honestly, keep your documents ready, and always collect your No Dues Certificate after closing any loan. Compare loan types in our guide on personal loan vs credit card EMI before you decide.
Frequently Asked Questions
From when is the prepayment charge ban applicable?
It applies to floating-rate loans sanctioned or renewed on or after 1 January 2026, under the RBI’s Pre-payment Charges on Loans Directions, 2025.
Can my bank charge a fee if I close my fixed-rate personal loan?
Yes, possibly. The ban covers floating-rate loans. For fixed-rate loans, any prepayment charge must be disclosed in your sanction letter and Key Facts Statement.
Is there a lock-in period before I can prepay?
No. For covered loans, the directions do not allow a lock-in condition for prepayment.
Does the ban apply if I repay using another loan?
Yes. The exemption applies even when the repayment money comes from a balance transfer to another lender.

Sarthak Gupta writes about personal finance, loans and credit for Indian borrowers. His guides on Techy Loan explain CIBIL scores, RBI rules and loan apps in simple language so readers can borrow safely and confidently.